Opening 0:00
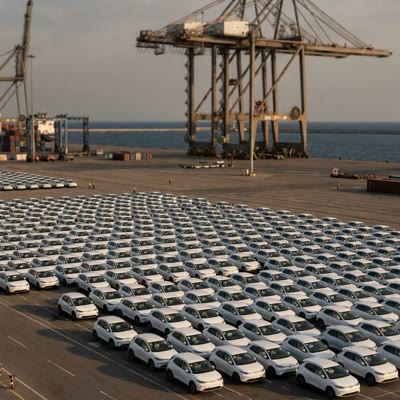
Welcome to today's China report. Today it's trade, supply chains and industrial overcapacity, five reports from this summer that all, in different ways, try to measure how much of the world's upstream industrial capacity actually sits in China, and what anyone else can do about it. One thing to say up front: three of the five aren't squarely on this topic. The Rhodium Group's is framed as an artificial intelligence paper, the Lowy Institute's is about Southeast Asia rather than China, and one of the two briefs from the European Council on Foreign Relations covers a single sector. I'll say why each earns its place, and I won't ask any of them for claims they never made.
MERICS on the 15th Five-Year Plan 0:42
Start with the Mercator Institute for China Studies, MERICS, published on the twenty-ninth of July by Andreas Mischer and Alexander Brown. The claim is that China's fifteenth Five-Year Plan bets everything on technological self-reliance, and the money to deliver it isn't there.
The mechanism is specific, and it's the best thing in the report. Industrial policy in China is mostly paid for locally, the report says local governments account for over eighty-five percent of general public budget spending, and the central government spends under ten percent of its budget on industrial policy. So if you want to know whether the plan gets funded, look at local balance sheets. And those are ugly: local debt of forty-eight trillion yuan officially, ninety to a hundred and ten trillion once you count off-balance-sheet financing vehicles, against a GDP of a hundred and thirty-five trillion. Fixed-asset investment fell four point one percent in May twenty twenty-six. Private investment fell eight point five percent in June. Total factor productivity growth went from over four percent a year in the two thousands to one point seven percent from twenty twenty to twenty twenty-three. Youth unemployment, sixteen point nine percent in March. So exports become the release valve, roughly thirty percent of last year's growth, on a record trade surplus of one point two trillion dollars.
Where does that rest? Almost entirely on Chinese official statistics, the finance ministry and the statistics bureau, plus the Penn World Table for the productivity series. That's actually fine here, because those sources cut against Beijing's interest: if the official numbers say distress, the real number is unlikely to be better.
Here's my problem. The report shows the fiscal squeeze. It doesn't show the squeeze binding. Chinese local finances have been called unsustainable for a decade, and capacity got built anyway. What would settle it is disbursement data, do actual industrial-policy outlays in the twenty twenty-six and twenty twenty-seven budgets fall, sector by sector? The report doesn't have that, and it makes no recommendations, which is honest.
Rhodium on the AI stack and minerals 2:43
The Rhodium Group, the fourth of August, Reva Goujon and colleagues. It's called an AI strategy paper. It's really a supply-chain audit, which is why it's here.
The argument: American policy obsesses over chips, cloud and frontier models, while China competes across all eight layers, including the physical ones. And vulnerabilities cascade upward, scarce germanium constrains fibre optics, which constrains data centres. From there: no single Western country can match a protected home market at that scale, so it has to be a pooled G7-plus coalition.
The evidence is mixed in a way worth naming. Ninety percent of critical mineral refining comes from the International Energy Agency. The Hugging Face download share, forty-one percent Chinese models against thirty-one percent American, is platform data. Memory market share is Counterpoint Research. The humanoid robot component figure is from a venture capital firm's analysis, and the claim that a Tesla robot costs a hundred and eighty-five percent more without Chinese parts is Morgan Stanley's. Those are all outside sources, cited. The two hundred and eighty gigawatts of Chinese data-centre power by twenty thirty is Rhodium's own model, and you can't check it.
Two challenges. Downloads aren't deployment. A download share measures what developers try, not what runs in production, and the report leans on it as a deployment metric. Second, the twenty thirty-five scenarios are explicitly thought experiments, and the report says so, but the "winning" one contains a fifteen percent aligned tariff on Chinese goods as an assumption, not as a modelled result. That's a policy preference wearing a scenario's clothes.
ECFR on Europe's swarm strategy 4:26
Andrew Small for the European Council on Foreign Relations, the seventeenth of June. Europe's sector-by-sector defence has failed, he argues, because it hands Beijing one clear target at a time. Instead: fifty-plus dispersed measures at once, a swarm, anchored in six non-negotiable conditions for single-market access.
The mechanism is the interesting bit. Each measure is small enough that focused retaliation isn't worth it; together they reshape access. And if Beijing does retaliate, that's a political opening, not a defeat.
The evidence for the diagnosis is strong: China's record quarterly surplus with the EU, eighty-three billion euros in the first quarter of twenty twenty-six. The best single data point is French: Chinese electric-vehicle market share in France collapsing from thirty-two percent to four percent within months after France tied subsidies to carbon footprint. That's the mechanism working.
But look at it closely and it cuts the other way. That was one loud, visible, single-country measure, exactly what the swarm theory says to avoid. The core claim, that dispersed sub-threshold measures escape retaliation, isn't demonstrated anywhere. It's asserted. And one of its sharpest figures, five hundred European manufacturing jobs lost a day, comes from Rhodium, the same shop as our second report. Agreement between think tanks reading each other isn't independent confirmation.
Lowy on Southeast Asia's supply chains 5:56
Robert Walker at the Lowy Institute, the fifth of July. Southeast Asia rather than China, but it measures what Chinese industrial gravity plus American decoupling does to everyone in between.
The argument is triage. Strategic supply chains are over twenty percent of regional exports and half of inbound investment, and they grew at seven point seven percent a year against two point seven for everything else. Back semiconductors, back electric vehicles and batteries, stop subsidising critical minerals and solar.
The data is real trade data, UN Comtrade, fDi Markets, customs figures. Two hundred and fifty-eight billion dollars of chip exports in twenty twenty-three, twenty-eight percent of the world's. Solar exports to the United States down eighty-five percent after the June twenty twenty-four duties. And the sharpest number in the paper is an embarrassment: forty-four billion dollars of electric-vehicle and battery investment since twenty sixteen, and Thailand, the region's biggest exporter, shipped three hundred and seventy-seven million dollars of finished EVs in twenty twenty-four while importing over five times more than it exported.
The weak link is the semiconductor recommendation. It works because Washington exempted chips from the twenty twenty-five reciprocal tariffs. That's a policy choice, revocable at any time, and the entire priority ranking rests on it staying put.
ECFR on fermentation capacity 7:25
Last, Janka Oertel and Nina Schmelzer for ECFR, the third of July, on biomanufacturing. One sector, before the surge, which is why it's useful. It tests the solar-and-batteries mechanism in advance.
The claim: China holds over seventy percent of global basic fermentation capacity, has a twenty thirty-five leadership target, and named thirty-five flagship products last July. Europe invents and China scales, again, unless Europe treats fermentation tanks as strategic infrastructure.
The hardest evidence is European and unflattering: novel food approvals averaging two and a half years, up to six; biopesticides seven to nine years. That's measurable, and it supports the recommendation directly. The interviews, industry representatives in Copenhagen, Brussels and Berlin over a year, are honestly labelled.
But the load-bearing number, that seventy percent, is sourced to a People's Daily article. A state newspaper's capacity figure is a thin foundation for a chokepoint claim. And basic fermentation means commodity amino acids and citric acid, the brief's own figures show Europe ahead in precision fermentation, and Chinese producers importing microbial strains from Denmark. That's a dependency running the other way, and the brief mentions it without weighing it.
What to watch 8:50
Two things would move me. First, actual disbursement data: if Chinese local industrial-policy spending falls in the next two budget cycles, MERICS is right and the capacity story slows. Second, an independent plant-level audit of fermentation capacity split by type, that turns a newspaper number into a fact.
And note the real contradiction. MERICS describes a China leaning on exports out of weakness. Rhodium and both ECFR briefs describe Chinese scale as a compounding strategic asset. Both can be true at once, but they point to opposite European timelines: act now, or wait them out.